

In 1967, a Maasai herder named Jumanne Mhero Ngoma stumbled across a cluster of striking violet crystals in the Mereli Hills near Arusha, Tanzania. For his historic discovery, Ngoma was compensated with 50,000 shillings roughly $22 in today’s valuation. Meanwhile, the commercial rights to market the gemstone were handed to Henry B. Platt, then vice president of Tiffany & Co. Platt famously named the stone “Tanzanite” and launched an iconic global campaign boasting that the jewel could only be found in two places: “Tanzania and Tiffany’s.” Between 1967 and 1971, miners extracted an estimated two million carats of Tanzanite, generating wealth that largely bypassed the nation of its origin. Today, those early yields would be worth an estimated $1.2 billion.
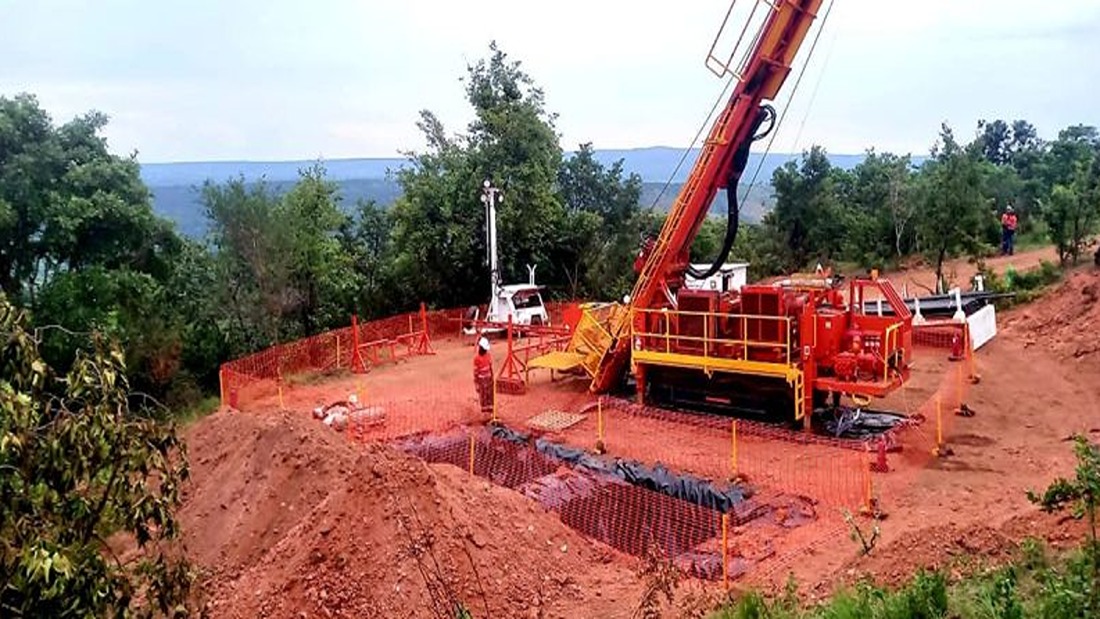
For decades, this story served as a textbook case of African mineral wealth being siphoned off by external actors. Yet, as primary industries across the continent re-examine their supply chains, Tanzania is executing a dramatic turnaround. The nation’s mining sector has undergone rapid growth and diversification, officially overtaking tourism in the mid-2000s as the country’s main driver of foreign currency. Since 2021, state revenues from mining taxes and royalties have more than doubled, with gold exports climbing 38.2% last year to a record $4.7 billion. With mining’s contribution to national GDP officially crossing the 10% threshold, the state is expanding into mineral sands at Fungoni-Kigamboni and Tajiri, a new processing plant in Tanga, and a government-sanctioned niobium development at Panda Hill poised to place Tanzania among the world’s top four producers.
This shift is anchored by a deliberate legislative overhaul designed to ensure local populations retain a fair share of land-derived wealth. Amendments to the Mining Act now grant the Tanzanian government a mandatory 16% non-dilutive, free-carried interest in large-scale operations, complemented by strict local content rules requiring domestic equity stakes across project supply chains. President Samia Suluhu Hassan has framed this commercial framework as “sovereign pragmatism,” transitioning the state from a passive royalty collector into an active commercial partner. Combined with streamlined land titling and improved judicial efficiency, the reforms have successfully defied early fears of investor flight, attracting approximately $3.3 billion in private capital over the last four years.
“Tanzania is demonstrating that a nation can assert firm regulatory boundaries without closing its doors to international markets,” notes a regional energy and trade analyst. “The transition from passive resource collection to active equity participation marks a fundamental turning point for domestic value addition.”
The cornerstone of this new strategy lies in moving up the supply chain through domestic refining. A primary test case is the Kabanga nickel deposit one of the world’s largest undeveloped battery-grade nickel sources. A U.S. government-backed consortium, Orion CMC, alongside Abu Dhabi’s L’imad Holding, is finalizing plans for a domestic refinery to supply the global electric vehicle market. The syndicate is currently negotiating a $500-600 million stake in the project as Western powers seek to diversify critical mineral supply networks.
While the broader momentum remains strong, the jurisdiction faces the typical friction of rapidly expanding resource markets. Western-linked graphite developments, such as the Nachu project and the world-class Mahenge deposit, have navigated corporate restructuring and shifted investment timelines. Yet, industry observers view these delays as standard growing pains within a transforming market. By securing capital across U.S., Chinese, and Gulf partners simultaneously, Tanzania has insulated its industrial model against single-market volatility, offering a blueprint for other resource-rich nations aiming to retain value at the source.